
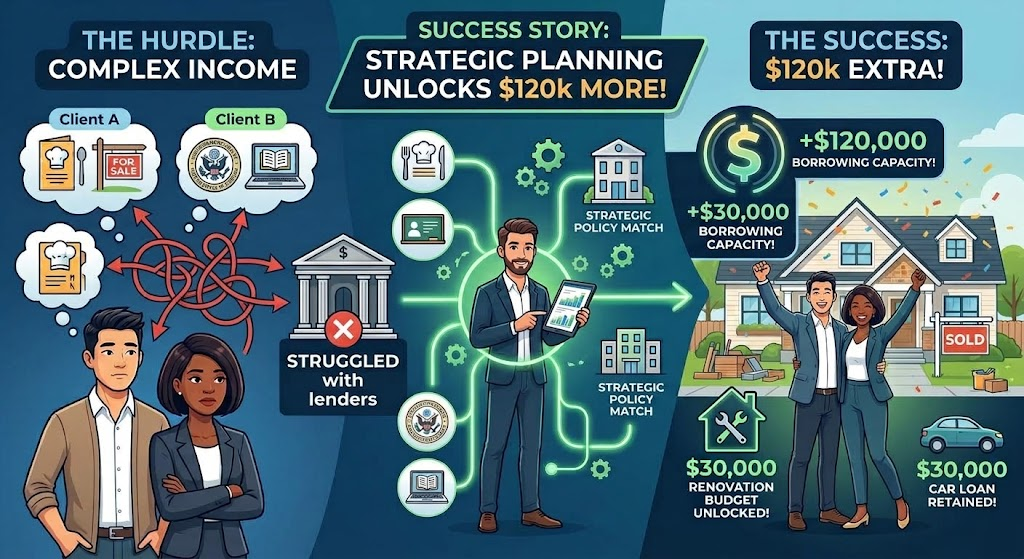
Client Profile: First-Time Homebuyers (Millennial Professionals)
Income Structure: Dual T4 Position + Self-Employed Side Hustles
Primary Strategy: Understanding, Packaging & Presenting Non-Traditional Income to the correct lenders
Key Results: Increased Borrowing Capacity by $120,000 and financed $30,000 in renovations
The Challenge: Modern Income vs. Rigid Lending Rules
A couple approached me ready to buy their first home together. Like many modern professionals, their income stream was diversified:
- Client A: Worked part-time in the restaurant industry alongside an active real estate practice. Due to market shifts, recent year-to-date real estate earnings were lower than the previous year.
- Client B: Held a temporary full-time position with the government, supplemented by a part-time teaching role.
These clients were unsatisfied with the amount their lender qualified them for and required them to pay-off their vehicle loan.
The Advisory Approach
Instead of taking “no” for an answer the clients came to me for a second opinion. Upon looking at the file, we could see there was strength in the multiple income streams if they were presented with the necessary documentation to the lender with correct policies.
The Data-Driven Result
By matching the clients’ specific scenario to a lender with aligned policy guidelines, we completely redefined their financial position:
- +$120,000 in Borrowing Power: Secured an additional $120,000 in total qualifying limit compared to the next best lender response.
- $30,000 Debt Retained: Avoided a mandatory condition requiring them to pay off a $30,000 auto loan out-of-pocket, preserving their cash reserves for the down-payment.
- $30,000 Built-In Renovation Budget: Leveraged the increased qualifying capacity to roll $30,000 of immediate home improvement costs directly into the primary mortgage.
The clients successfully purchased a property they loved—and had the immediate capital to customize it without depleting their emergency savings.
Key Takeaway: A decline from one lender rarely means you can’t buy. It often just means your broker hasn’t matched your specific income structure to the right underwriting policy yet.